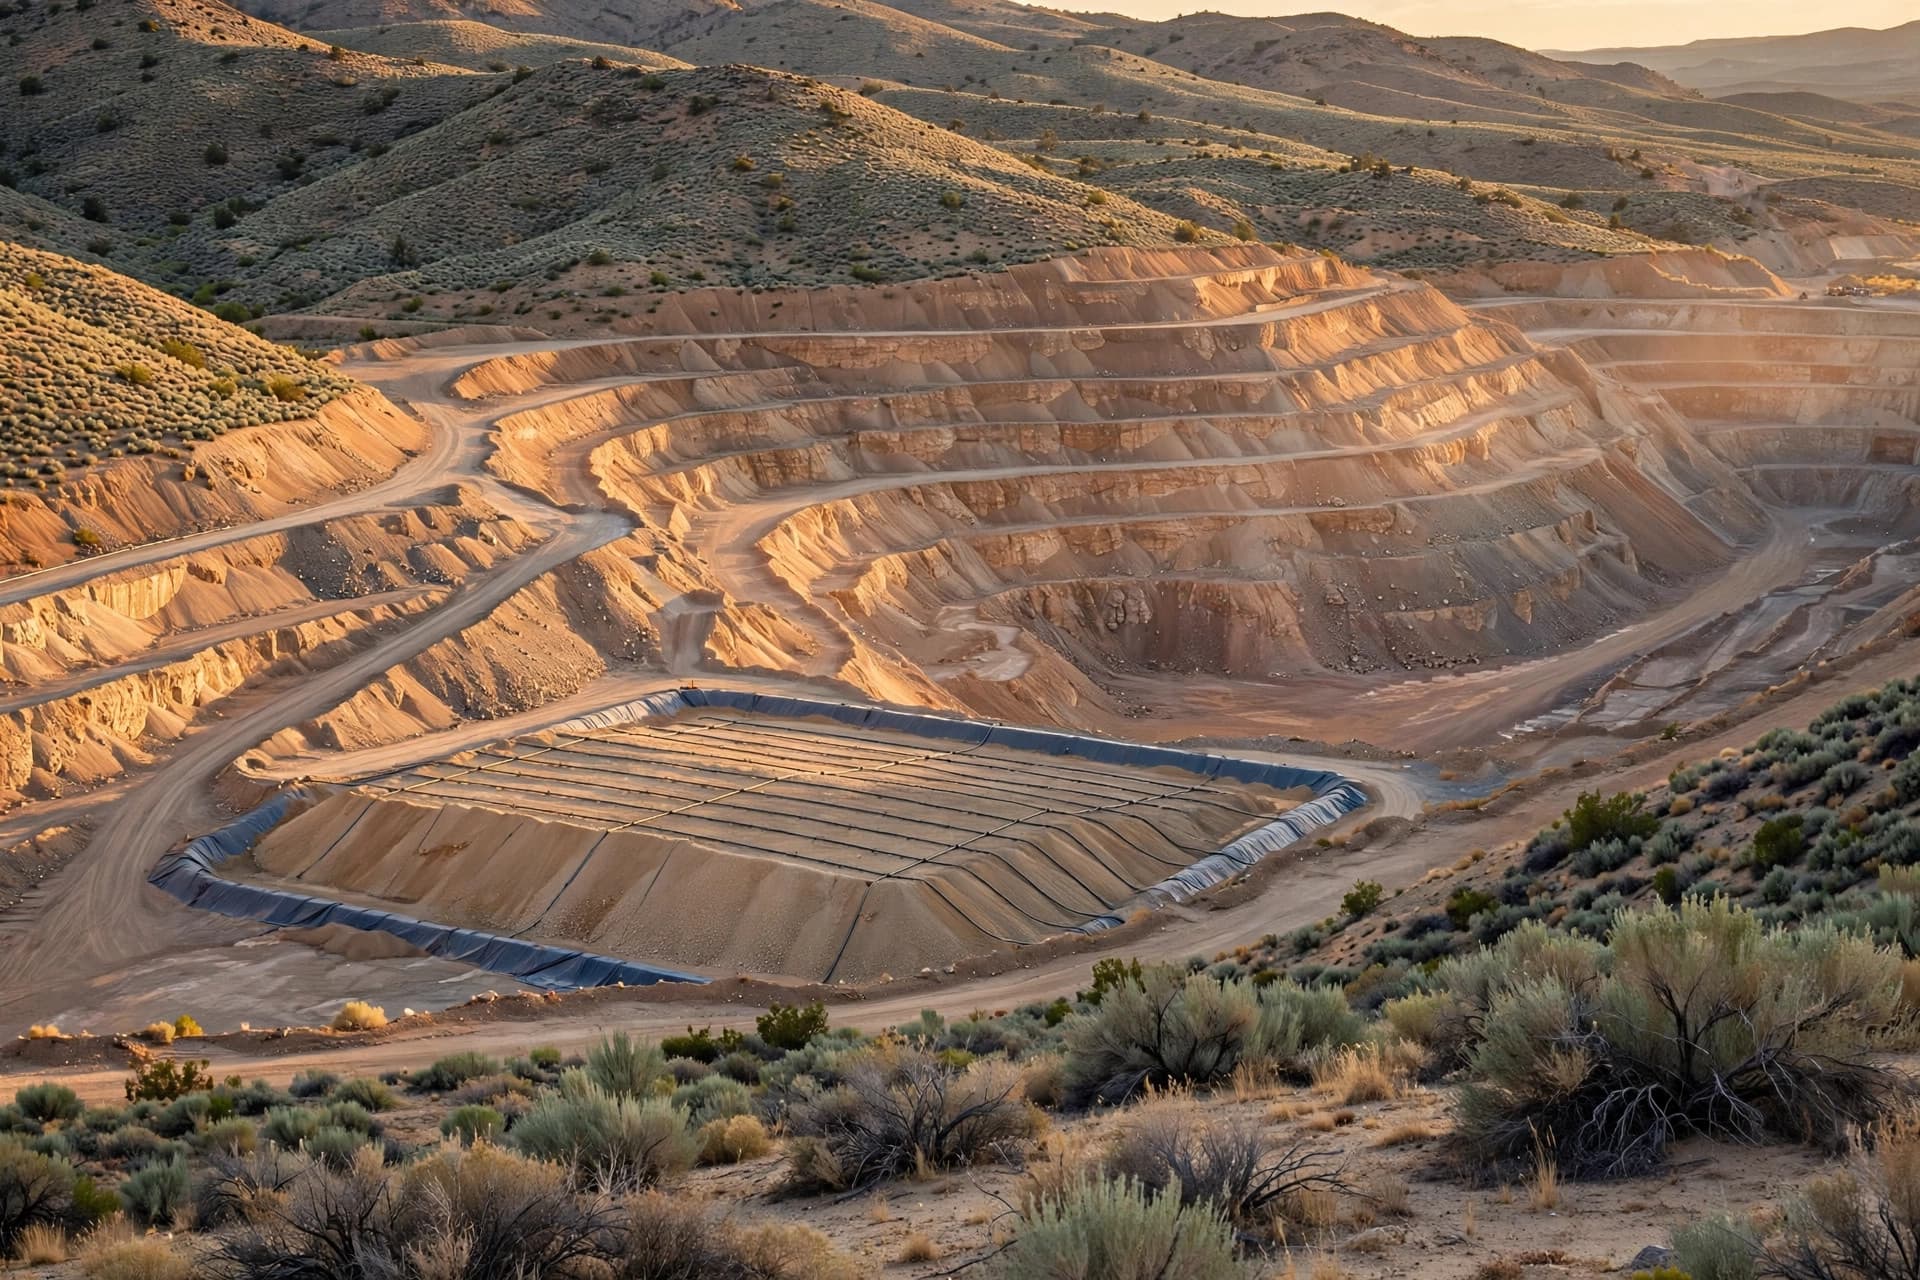
Santa Fe is a past-producing mine in Nevada's Walker Lane that Lahontan wants to put back into production. The updated study released October 14 gives that restart its most detailed numbers yet — and its clearest list of what still has to happen first.
- The updated preliminary economic assessment (PEA) puts post-tax NPV at a 5% discount rate at US$820 million, with a post-tax IRR of 40.1%, at base-case prices of US$3,600/oz gold and US$49/oz silver.
- The plan runs for an 11-year active mine life plus one year of residual leaching, across the Santa Fe, Calvada, Slab and York deposits, using open-pit mining and conventional heap leaching.
- Average annual output is put at about 91,900 gold-equivalent ounces — roughly 88,300 ounces of gold and 254,000 ounces of silver a year — rising to about 112,500 Au Eq ounces in years 4 through 11.
- Initial capital is estimated at US$172 million, including a US$22.2 million contingency, with a payback period of 3.7 years at base-case prices.
- Estimated gold cash costs are US$1,909/oz and all-in sustaining costs US$2,250/oz. The company says the new post-tax NPV is more than fourteen times the figure in its 2024 PEA.
What the plan actually is
Material from the four deposits would be mined by a contractor fleet, crushed in three stages and stacked on a multi-lift heap leach pad, starting at about 12,500 tonnes per day for the first three years and expanding to about 17,000 tonnes per day after that. Gold and silver would be recovered through a carbon adsorption-desorption-recovery plant and poured as doré on site. Sulfide material from the Santa Fe pit would be pre-oxidised before leaching.
The mine plan and production schedule are not just an investor document. Lahontan says they will feed the final Mine Plan of Operations it submits to the Bureau of Land Management, that environmental baseline studies are complete, and that it expects to obtain the federal and state permits needed for construction in 2027. Its stated production target for Santa Fe remains 2027.
The honesty box
A PEA is the earliest form of economic study, and this one is explicit about its own limits. It is preliminary in nature, it includes inferred mineral resources — the least certain category — and the company states it has not defined any mineral reserves at Santa Fe. Mineral resources that are not reserves do not have demonstrated economic viability, and there is no certainty the PEA outcome will be realised. The economics also lean on metal prices well above historic norms: the base case uses US$3,600 gold, and at the lower case in the study's own sensitivity table (US$3,000 gold, US$30 silver) post-tax NPV falls to about US$476 million.
What to watch
The supporting technical report, due within 45 days of the release; the Mine Plan of Operations submission and the 2027 permitting timeline; and exploration beside the known deposits and at the historic heap leach pads, which the company flags as its main route to growing the resource the plan is built on.